- The macro is in focus through month-end, but investors must not overlook company-level trends in the days ahead, including an active conference circuit
- Stocks remain resilient despite higher Treasury rates and Fed hiking, with the S&P 500 near record highs, led by tech
- Jobs data, consumer spending, and corporate guidance will be key signals as investors eye Q4 volatility catalysts and 2027 forecasts
It’s really starting to feel like autumn now. August PPI, CPI, and Retail Sales are in the books, the September FOMC meeting is out of the way, and we can now look forward to Jobs Week on Wall Street. Football is in full swing, and earnings season begins before you know it, with Pepsi (PEP) posting results on Thursday, October 8, followed the next morning by Delta (DAL).
Tuesday, October 13, is the Super Bowl for the Financials sector. That’s when JPMorgan Chase (JPM), Wells Fargo (WFC), Citigroup (C), and Goldman Sachs (GS) report July through September numbers. Bank of America (BAC) and Morgan Stanley (MS) then report on Wednesday, October 14. Before the Q3 earnings deluge, keep your eye on Costco (COST) this Thursday evening.
Earnings Have Been a Treat
Will there be a slew of October surprises in store from corporate America? Hard to say, but if the recent trend holds, it might not be all that spooky. Consider that the S&P 500 reported earnings growth of more than 50% YoY in Q2, the best growth rate in five years, according to John Butters at FactSet. Profits were driven by operations, for sure, but several seemingly one-time factors supported the EPS surge.
For instance, “other income” related to gains on private investments helped the Information Technology sector, soaring oil prices fueled Energy-sector earnings, tariff refunds aided consumer areas, not to mention intense AI-powered capex feeding directly to the bottom lines of semiconductor companies.
Inflation is Tricky
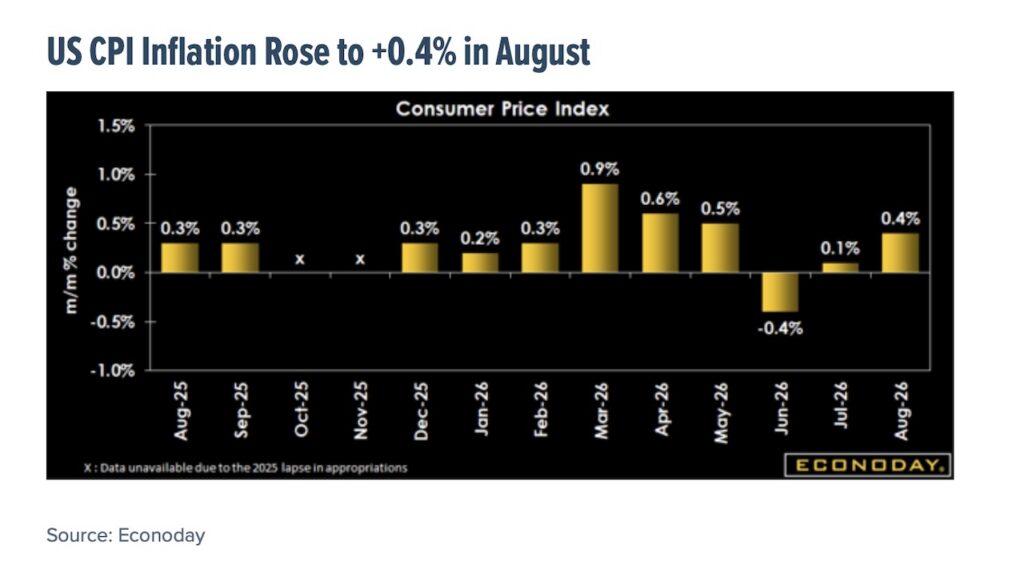
AI players have also been active on the debt-issuance front. Partly for that reason, the Fed hiked rates on September 16. The move wasn’t unexpected, but it didn’t come without a dose of controversy. Some macro pundits assert that the current 3.7% PCE Price Index inflation rate will naturally cool, given subsiding effects of tariffs, the conflict in Iran, summertime software price spikes, and questionable recording of portfolio management cost increases. More hawkish Wall Street economists underscore that at some point, a series of “one-off” factors can no longer be framed as a temporary phenomenon, and that a new macro-volatility backdrop is upon us.
What does the market say? Perhaps some central bank tightening is workable. Consider that the 2-year Treasury yield has come within a quarter point of 5%, and the Fed Funds futures market prices in three more hikes by Q3 2027. It’s as if the market relays to the FOMC that taking back the three insurance cuts executed over the final four months of 2025 would not be a policy mistake.
US CPI Inflation Rose to +0.4% in August
Tech Stocks Are Powering Markets Again, Leaving Some Cyclicals Behind
Another indicator? Stock prices. The S&P 500 is within a percentage point of its August 14 all-time high. The Nasdaq 100 may have broken out from its Q3 downtrend. International indexes are knocking on new highs. While breadth could be better (the Mag 7 is leading once again), equities appear to have no problem with higher borrowing costs.
It’s not all roses, however, with cyclical sectors like Industrials, Consumer Discretionary (ex-Amazon and Tesla), and areas of Financials still well off their 2026 highs. U.S. small- and mid-cap stocks didn’t exactly have a banner summer, either.
Main Street Feels the Squeeze, Though the “K” May be Closing
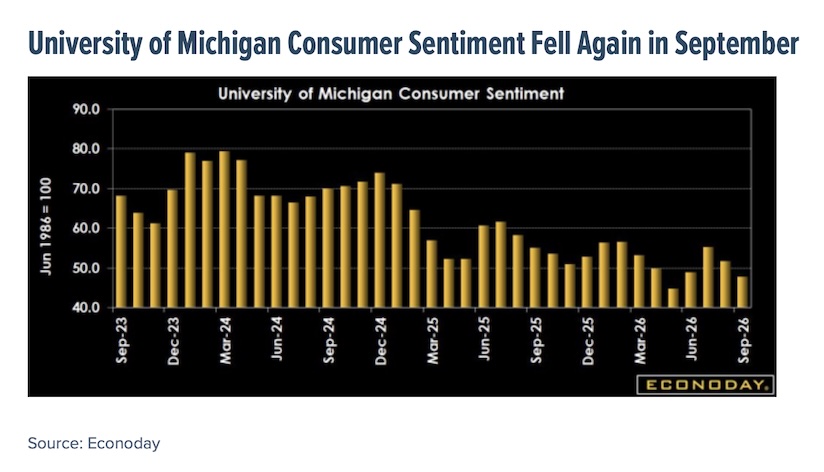
Further Fed tightening could do additional damage to indebted households, too. According to Econoday, the most recent University of Michigan Surveys of Consumers revealed a top-five weakest sentiment reading. Stubbornly high gas prices and soaring diesel sting Main Street, with higher energy costs likely to seep into what we all pay at the grocery store by the time the holidays roll around.
University of Michigan Consumer Sentiment Fell Again in September
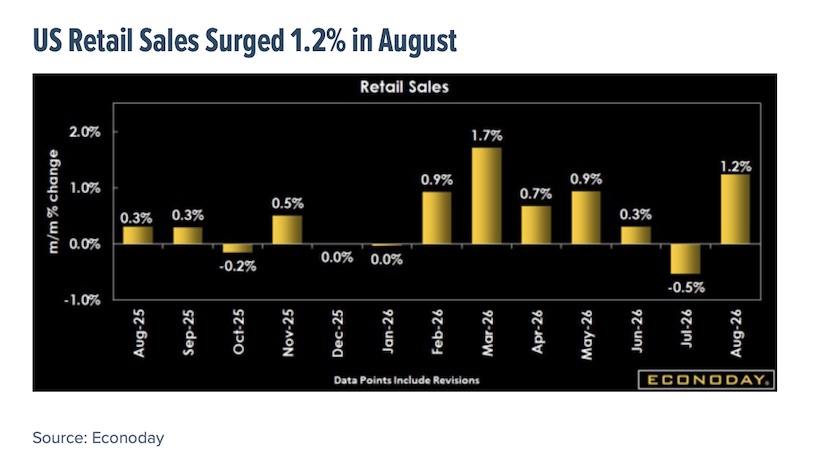
“UMich” has been ugly, but official August Retail Sales numbers put out by the U.S. Census Bureau were downright gaudy. The key back-to-school shopping season appeared to be a strong one, even backing out gasoline expenditures. Online spending, electronics & appliances, sporting goods, and even restaurant activity were impressive.
The top half of income earners always carries the bulk of the load, but, as some BofA card-spending data show, the “K-shaped” economy has normalized since the start of 2026. The bottom 50% of the workforce has seen improved wage growth, and they have stepped up their discretionary spending.
US Retail Sales Surged 1.2% in August
Gaming Out 2027
All of this leads into the Q4 conference season, when investors get their first look at CY 2027 forecasts from the world’s most important companies. Executives have weathered many macro storms since 2020, and today’s challenges come with just as many opportunities. New technologies, global growth, and strong capital markets could result in bold projects and long-term investments. Our team will keep tabs on the latest developments over the coming weeks.
The Bottom Line
Following major August data and the September Fed meeting, traders get a chance to catch their breath ahead of the Q3 earnings season. Jobs data starts rolling in Wednesday next week, with the November midterm elections coming closer into view. While eyes are on the macro, investors must heed guidance from the corporate world on their plans for the year ahead.
Twitter: @ChristineLShort
The author may hold positions in mentioned securities. Any opinions expressed herein are solely those of the author, and do not in any way represent the views or opinions of any other person or entity.